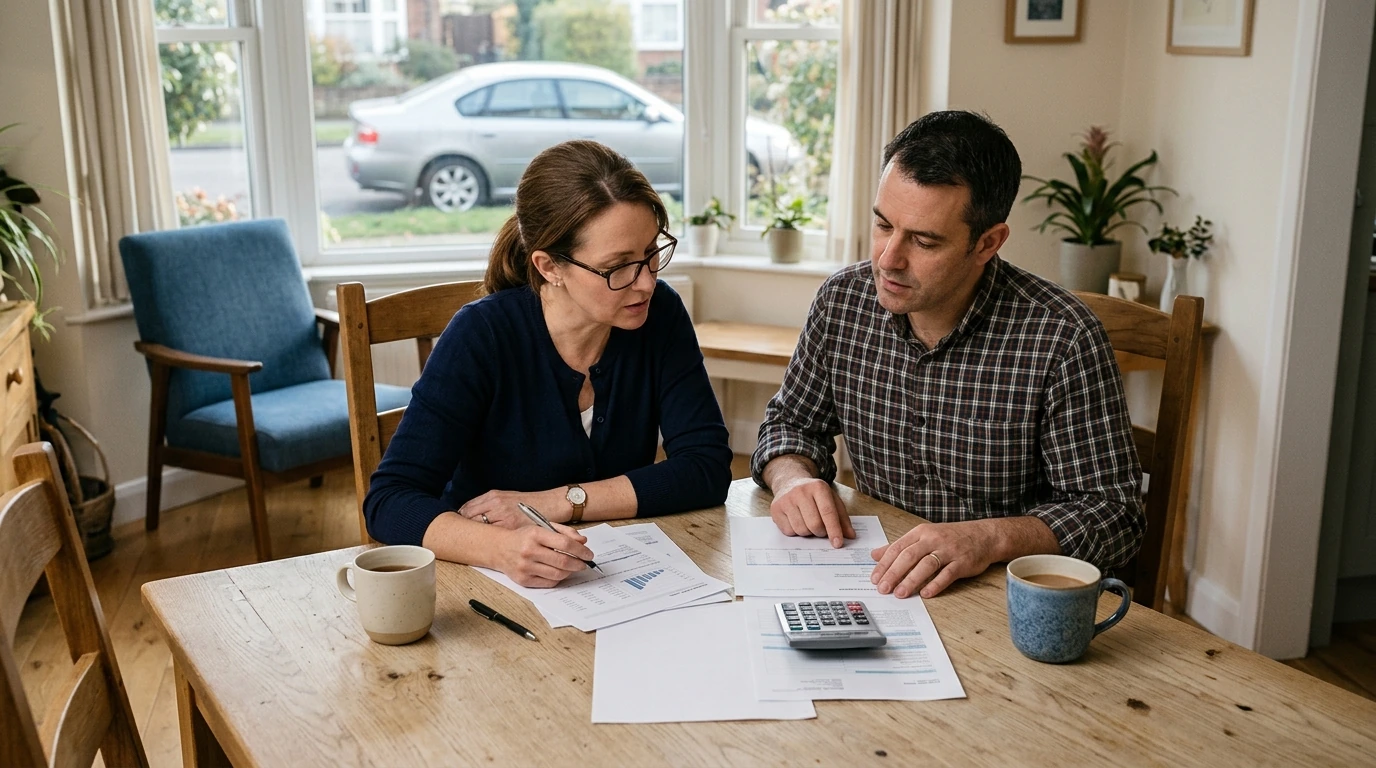
Cosigning a Car Loan: Benefits, Risks, and Key Questions
A cosigner promises to repay the loan if the primary borrower does not. Depending on the agreement and applicable law, the lender can generally seek payment from the cosigner without first exhausting collection efforts against the borrower. That obligation can include more than a single missed payment if the loan falls seriously behind.
Signing the loan is not the same as owning the car. The names on the title, any separate agreements, and applicable state law determine rights to use, possess, or sell the vehicle. Both people should read the loan agreement and title documents before signing, rather than assuming the paperwork says what they discussed. The Consumer Financial Protection Bureau’s explanation of cosigning is a useful starting point for that conversation.
A lender may consider a cosigner’s credit history and income when evaluating an application. That could improve the borrower’s chance of approval or the terms offered, but neither outcome is guaranteed. There is no single credit score that ensures approval with a cosigner.
Compare written offers using the APR, number of payments, monthly payment, and total amount paid. A longer term may reduce the monthly payment while increasing total interest. Both people should understand the full commitment, not just whether the next payment fits the budget.
Featured in this guide
Navigating Cosigners for Car Loans: A Complete Guide to Understanding, Benefits, and Risks of Cosigning
Late payments or default may affect both people’s credit, and the debt may affect the cosigner’s ability to borrow for another goal. Agree on how you will monitor payments, who will receive account notices, and when the borrower will raise a budget problem.
Discuss what you would do if payments became unaffordable, including whether selling the car or applying to refinance would be possible. Do not assume you can request removal from the loan later: refinancing or another lender-approved arrangement may be required, and approval is not guaranteed.
Check the product’s listed specifications when evaluating make a plan before payments begin.
Ask the lender whether the cosigner must appear in person, how identity verification works, and which documents each person must sign. Before signing, compare the final APR, term, payment, and total repayment amount with the offer you expected. Confirm whose name will appear on the title, and keep copies of the signed documents.
Before moving ahead, ask three questions plainly: Can the borrower afford the payment without help? Could the cosigner cover it if necessary? Do both people understand the title arrangement and what it would take to end the cosigner’s obligation? If either person needs time to review the terms or seek advice, pause the purchase. A comfortable decision matters more than finishing the paperwork that day.
Compare related options such as Low-Maintenance Pets | A Practical Guide to the Best Low Maintenance Pets for Busy Lives & Small Spaces to match features, dimensions, and use case before choosing.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
It is also worth checking measurements, material notes, included parts, and compatibility details so the item matches the way it will be used after delivery.
Cosigning the loan alone does not necessarily give you ownership or a right to drive the car. Review whose name is on the title and the rules in your state.
Requirements vary by lender and dealership. Ask how identity verification and loan documents must be completed before you schedule a visit.
A cosigner does not gain the right to take the vehicle merely by signing the loan. Ownership and possession depend on the title, any separate agreements, and applicable law.
There is no single score that guarantees approval. The lender evaluates the application under its own standards, including credit, income, debt, vehicle details, and loan terms.

Leave a comment